Step 4 of the ASC 606 revenue model requires entities to allocate the transaction price to the performance obligations. To do this, the standalone selling price (SSP) of each item must first be determined. This article illustrates the process of estimating SSP by providing a comprehensive example. The following key accounting issues are addressed in the article:
- When should the residual approach be applied to multiple items to establish an aggregate SSP?
- What factors should be considered when using the adjusted market assessment approach?
- What factors should be considered when using the expected cost-plus margin approach?
- How is the relative SSP method applied to allocate transaction price?
The basic accounting principles involved in this example are discussed in Standalone Selling Prices in ASC 606. This article applies those principles to a set of hypothetical facts created to showcase these points. This article also provides examples of real companies and how they apply these concepts.
Background for SmartHomes Inc.
SmartHomes Inc. (SmartHomes), a vendor of home-automation equipment, sells a single hub called the “Home Uploading Base” (HUB) through a large online retailer in the United States. The HUB connects to several items, including lights, locks, thermostats, and doorbells, all of which are sold separately by third parties. The system also connects wirelessly to the products through the “SmartHomes App,” which allows the HUB to use an internet connection to communicate with additional third-party products through the HUB. SmartHomes identifies three performance obligations in this contract: (1) the HUB and SmartHomes App (combined), (2) post-contract telephone support, and (3) post-contract maintenance.
The app itself is not “capable of being distinct” because it does not provide value to the customer without the HUB and is combined with the HUB as one performance obligation. In its first year of business, SmartHomes priced the HUB using a variable pricing structure based on the quantity of third-party items purchased by the customer. The purpose of the variable pricing structure is to encourage integration of the HUB with the third-party items. The HUB regularly sells at prices varying between $30-$80, and SmartHomes is unable to establish an observable selling price.
Included in these transaction prices is one year of post-contract maintenance that may be renewed on a yearly basis for $20. SmartHomes also provides post-contract telephone support for technical problems involving the HUB within the first year after the date of purchase. The telephone support is not offered on a stand-alone basis.
Several competitors sell home-automation equipment similar to the HUB. After performing an extensive analysis of the United States market, SmartHomes concludes that similar home-automation equipment sold in retail outlets is priced between $50-$90, excluding any additional post-contract maintenance. SmartHomes estimates the cost of telephone support is $8 per customer. SmartHomes determines that a $2 margin reflects what the market would be willing to pay for telephone support.
SmartHomes enters a contract with a customer to provide a HUB (including the year of maintenance) for a price of $80. Using the information provided above, what are the SSPs of a HUB (including the “SmartHomes App”), a year of telephone support, and a year of maintenance? Furthermore, how should SmartHomes allocate the transaction price to the performance obligations in the contract?
Accounting Analysis
The best evidence of an SSP is the price at which the entity sells a promised good or service separately to a customer. If an observable price is not available for a promised good or service, the guidance permits the use of any reasonable estimation method that maximizes observable inputs, provided the method is applied consistently in similar circumstances. Though the guidance allows for other estimation methods, this analysis will focus on the following three methods because they are specifically mentioned in the guidance: the residual approach, the adjusted market assessment approach, and the expected cost plus margin approach.
Observable SSP
SmartHomes regularly sells the post-contract maintenance for a price of $20 per year with an option to renew the contract at the end of each year. Because this is the only price that SmartHomes offered for maintenance over the past year, the entity concludes that it has observable evidence to establish $20 as the SSP for post-contract maintenance.
Residual Approach
Because the HUB/App and the telephone support are never sold separately, a standalone selling price must be estimated for each item. The residual approach is potentially useful in this situation, but it can only be used if two conditions are met. First, at least one of the performance obligations must have an observable standalone selling price (maintenance in this example). Second, the residual approach can only be used for the remaining performance obligations if
- the price of the goods or services is highly variable or
- the goods or services have not previously been sold on a standalone basis.
For more on the residual approach, see Standalone Selling Prices in ASC 606.
KPMG defines highly variable as a product or service sold to different customers at or near the same time for a broad range of prices. Because SmartHomes sells the HUB to different customers around the same time at prices between $30-80, the prices are considered highly variable. Based on these criteria, the residual approach may be applied to estimate the standalone selling prices of both items in the contract: the HUB/App, due to its highly variable pricing, and the telephone support, as it has not been previously sold on a standalone basis.
The revenue standard permits the use of the residual approach to estimate the combined standalone selling price of multiple items—in this case, the HUB/App and telephone support. After determining this aggregate amount, other estimation techniques can be applied to allocate value to each performance obligation. Under the residual approach, post-contract maintenance is assigned $20, as it is regularly sold on a standalone basis and has an observable price.
The following table shows the value of the aggregate standalone selling price for the telephone support and HUB using the residual approach:
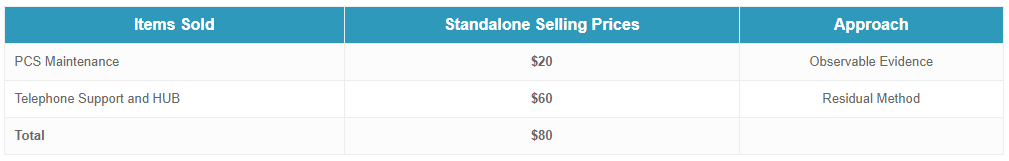
After removing the $20 for PCS maintenance, the residual method results in $60 as the aggregate standalone selling price for the HUB and telephone support. The $60 would then need to be allocated between the HUB and the telephone support according to their separately estimated standalone selling prices, as explained in the following sections.
Varonis Systems, Inc. (2019 SEC Correspondence): Use of Residual Value as an SSP Approach
Varonis, a data analytics company, shared correspondence with the SEC regarding the company’s SSP analysis for software licenses. Varonis sells software licenses in a package with maintenance and professional services, both of which are sold on a standalone basis. The SEC asked Varonis to include their analysis of the other approaches for evaluating the SSP of software licenses and how it determined them not to be appropriate. Varonis’s explanation is as follows:
- Adjusted market assessment approach: The Company’s software licenses contain proprietary technology that highly differentiates its licenses from the offerings of its competitors. Moreover, each of the Company’s individual products does not have a direct correlation with other products available in the observable market. The Company’s solution and offering differ from those of competitors, making competitor pricing even less relevant. Although published competitor list price information may be available, actual selling price information is not. Based upon the results of this analysis, the adjusted market assessment approach would not provide for the appropriate use of observable internal company inputs and/or third-party sales inputs in estimating SSP for the Company’s licenses.
- Expected cost-plus margin approach: There is no expected cost-plus margin approach available for the software component of the bundled packages. The Company’s software licenses do not have clear, identifiable fulfillment costs, so the expected cost-plus margin approach is not practical. Moreover, the Company’s selling and pricing strategies are focused on the value its products and solutions provide to customers and vary based on several factors, such as customer classification, the volume of users of each license, and the term of the license (whether perpetual or defined). In addition, estimating a margin based on what the market is willing to pay for the Company products cannot be done reliably given the multiple factors involved, including rapid changes in technologies offered in the marketplace, changes in customer spending behavior impacted by internal budget cycles and constraints and macroeconomic changes beyond the Company’s control. Based upon the results of this analysis, the expected cost-plus margin approach would not be appropriate to estimate an SSP for the Company’s licenses.
The Company does not sell software licenses on a standalone basis (i.e., unbundled) but does sell maintenance and PS on a standalone basis (i.e., optional maintenance renewals and additional PS hours). Since the SSP for maintenance and PS (if included) are directly observable, the residual approach can be used for the license for which observable inputs are not available if the pricing of the license is highly variable or uncertain in accordance with ASC 606-10-32-34(c).
This example illustrates how an entity should thoughtfully evaluate, and in some cases reject, the primary methods for estimating standalone selling price under ASC 606. Varonis demonstrates that when a product—such as proprietary software—lacks observable market comparables and does not have clearly identifiable costs, both the adjusted market assessment and expected cost-plus margin approaches may be inappropriate. In these situations, if other elements in the arrangement have observable standalone selling prices and the residual item exhibits highly variable or uncertain pricing, the residual approach may be justified. The key takeaway is that entities must support their SSP methodology with a clear, fact-specific analysis rather than defaulting to a single approach.
Adjusted Market Assessment Approach
The adjusted market assessment approach is used to determine the standalone selling price of the HUB and SmartHomes App. SmartHomes has found that similar home-automation equipment sold in retail outlets is priced between $50-$90, excluding post-contract support. SmartHomes considered the following criteria to estimate the standalone selling price of the HUB and SmartHomes App:
- Market Share – Home automation is a growing market, but SmartHomes entered the market last year and is trying to capture market share. As a relative newcomer, pricing the HUB at the higher end of the range would undermine the company’s strategy to capture market share quickly.
- Expected Profit Margin – Although SmartHomes is new to the market, it is selling to large online retailers, which requires the company to order its products in large volumes from its suppliers to meet customer demand. SmartHomes receives large discounts on high-volume purchases, which allows the company to meet its profit objectives at a lower price point than several competitors that sell in smaller retail outlets.
- Distribution Channel – Another advantage of selling through a large online retailer is a simplified distribution channel. Although the pressures to fill orders and move products are high when working with large retailers, companies can get their products into the hands of a large number of customers through a single bulk delivery to a single warehouse. Because SmartHomes works with a large retailer, the costs associated with the distribution channel are significantly lower than their competitors working with small retailers, which will allow SmartHomes to meet profit objectives at a lower price.
After considering these factors, SmartHomes determines the standalone selling price of the HUB and SmartHomes App to be $60.
Prothena Corporation Plc: Application of DCF Analysis for SSP
Prothena is a biotech company focused on discovering and developing treatments for neurological disorders, such as Parkinson’s disease. In 2019, the company entered into correspondence with the SEC due to the irregular nature and pricing of its products. The SEC asked Prothena to clarify how SSP for U.S. and Global Rights allocations were estimated for a large licensing contract with Celgene, a company based in Switzerland. Prothena described how it uses a discounted cash flow model to better determine the price, and how that model is equivalent to the adjusted market assessment approach. The company’s reasoning is as follows:
ASC 606 does not prescribe a single method to estimate a standalone selling price, but rather, requires entities to come to an appropriate estimate based on the facts and circumstances. ASC 606-10-32-33 requires that an entity use all available information in deriving an estimate of the standalone selling price, while ASC 606-10-32-34 identifies certain possible approaches. The Company believes its discounted cash flow approach is consistent with an adjusted market approach because the discounted cash flows are what a counterparty would use in determining how much it would be willing to pay for an optional right to obtain a license. Similarly, in determining the amount for which the Company would sell such a right, the Company considered the same assumptions outlined above.
Prothena argues that its discounted cash flow model serves as a practical way to estimate what market participants would pay, thereby aligning it with the adjusted market assessment approach. By grounding the valuation in expected future cash flows and risk-adjusted assumptions, the company attempts to replicate the pricing logic a third party would use in negotiating the transaction. The strength of this argument depends on whether those inputs genuinely reflect external market conditions rather than internal expectations.
Expected Cost Plus a Margin (Cost-Plus) Approach
The expected cost plus a margin approach is used to determine the standalone selling price of the telephone support. This approach considers the forecasted costs of fulfilling the performance obligation and adds a margin to the amount the market would be willing to pay. In determining the costs for the telephone service, SmartHomes considered the following items:
- Wages of personnel employed to provide the telephone support
- The cost of the telephone lines
- The cost of the telephone and computer equipment needed to provide the support
- The number of customers who are entitled to the telephone support
After considering these items, SmartHomes determines that the telephone support costs $8 per purchase of a HUB. SmartHomes’ internal expectation for margin on low-risk services is 25 percent. Accordingly, a $2 margin should be added to the cost to reflect what the market would be willing to pay for the telephone support. Considering these factors, the company estimates the standalone selling price of the telephone support at $10.
Kingsway Financial Services Inc.: Process of Calculating SSP
Kingsway Financial Services is a Canadian holding company with U.S. subsidiaries offering extended warranty, asset management, and real estate services. The company was approached by the SEC in a 2018 comment letter to explain how it reached the claim that the expected cost plus margin approach was most appropriate for the warranty SSP. Kingsway provided a detailed walkthrough of how they reached their conclusion.
First, the Company determines how much of the transaction price should be allocated to the other warranty services pursuant to the following methodology. Based on over 20 years of data regarding the number of calls the Company receives and activities performed related to complaints from homeowners or requests from homeowners and builders for dispute resolution services, the Company has estimated the costs related to these services. The Company uses historical data on complaints and dispute resolution requests in addition to the number of homes enrolled to calculate the percentage of complaints and dispute resolution requests received per enrollment per year of warranty coverage. This is then applied to all homes enrolled that are currently under warranty coverage to estimate the number of complaints and dispute resolution requests to be received by the year until coverage expires. The Company then calculates the average hourly cost of providing these ongoing services using actual payroll and other operating costs associated with those personnel performing these services, net of the additional average administrative fee the Company receives for the dispute resolution-related services, along with an estimate of the actual time spent on handling a complaint or dispute resolution request. A fully loaded cost is then calculated and applied to the estimates of complaints and dispute resolution requests over the remaining coverage period to estimate the total actual costs associated with the other warranty services performance obligation. To this cost, an estimated margin is applied based on the average profit margin on the Company’s revenue over four years. This margin is applied to the estimated total cost to arrive at an estimated cost plus margin amount. This cost plus margin amount is allocated to the other warranty services performance obligation and recorded as the homebuilder warranty service fee. The remainder of the transaction price, after allocating the portion to the other warranty services obligation, is allocated to the warranty administrative services performance obligation and recorded as the homebuilder warranty administrative fee.
Kingsway’s methodology reflects a structured application of the expected cost plus margin approach, grounded in extensive historical data and operational experience. By forecasting service activity levels, estimating fully loaded costs, and applying a consistent margin derived from historical profitability, the company builds an SSP that is both systematic and internally consistent with how it manages its business. The approach aligns with ASC 606 in form, but its strength ultimately depends on the reliability of historical trends and whether the applied margin appropriately reflects market-based returns rather than entity-specific performance.
Relative Standalone Selling Price Method
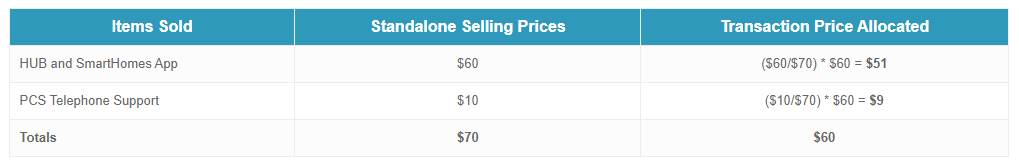
Once the standalone selling prices of the HUB and telephone support are determined, the remaining transaction price ($60) is allocated between the items using the relative standalone selling price method as follows:
Transaction Summary
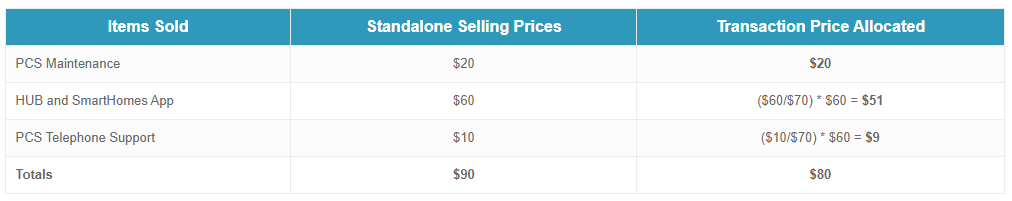
SmartHomes allocates $20 to PCS maintenance based on the observable price it charges its customers. The company uses the residual approach to determine an aggregate standalone selling price for the HUB/SmartHomes app and telephone support, which ensures that the maintenance is allocated at the full observable price of $20. After determining the aggregate standalone selling price of the HUB and telephone support, SmartHomes uses the adjusted-market assessment approach to determine the standalone selling price of the HUB ($60) and the cost-plus margin approach to determine the standalone selling price of the telephone support ($10). Using these values, SmartHomes applies the relative standalone selling price method to determine the amount of the remaining transaction price ($60) that should be allocated to the HUB ($51) and to the telephone support ($9). The following table summarizes the price allocation in this transaction.
Conclusion
This article discusses the process for estimating standalone selling prices to allocate the transaction price to performance obligations. It also provides an example of when the use of the residual approach may be appropriate to determine an aggregate standalone selling price for multiple items for which either (1) the prices are highly variable or (2) the items have not previously been sold on a standalone basis. When applying these examples, use professional judgment, as each situation is different in execution.
Editor’s Note
This article was reviewed in 2026 for consistency and correctness in accordance with present guidance. This case reflects guidance under ASC 606, Revenue from Contracts with Customers, as currently codified, including subsequent amendments. The concepts discussed remain relevant as ASC 606 has not undergone substantive changes regarding the estimation of standalone selling prices.
Resources Consulted


