Step 2 in ASC 606 Revenue from Contracts with Customers is to identify performance obligations in the contract. This means an entity must identify any promise to transfer “a good or service (or a bundle of goods or services) that is distinct” (ASC 606-10-25-14). In this article, we focus on the meaning of “distinct” and provide guidance, case studies, and SEC comment letters that clarify this concept.
Identifying a Distinct Good or Service
Once an entity has identified the goods or services promised in the contract, it must determine which goods and services are distinct. The FASB outlines two criteria that must be met for a good or service to be distinct (ASC 606-10-25-19):
1. The good or service is capable of being distinct.
2. The promise to transfer the good or service is distinct within the context of the contract.
A good or service is “capable of being distinct” if the customer can benefit from the good or service on its own or together with other readily available resources. In other words, a customer should be able to use the good or service in a way that economically benefits the customer without any other promised good or service in the contract. Several factors, such as the entity regularly selling the good or service separately, indicate that a good or service is capable of being distinct.
The promise to transfer a good or service must also be “distinct within the context of the contract.” The idea here is that promised goods and services in a contract sometimes depend on each other. In these cases, even though the promised goods and services are capable of being distinct on their own, the context of the contract suggests that the goods and services are being combined in a way that makes the whole significantly different from the individual parts. ASC 606-10-25-21 provides three indicators that goods or services are not distinct within the context of the contract and should therefore be combined as one performance obligation:
- Significant integration service. If an entity provides a significant service of integrating other promised goods or services in the contract, those goods and services should be combined into a single performance obligation. For example, in a house construction contract, plumbing, electrical, and flooring represent goods and services that are integrated into a single output (the house) for which the customer has contracted.
- Significant modification or customization. When promised services significantly modify or customize other promised goods or services in the contract, the goods or services being modified are not considered distinct from the modification service. This means the goods or services, and the modification service, represent a single performance obligation. For example, if an entity provides software and a customized installation that significantly modifies the software to work within the customer’s IT infrastructure, the customer can obtain no benefit from the software without the customized installation. Therefore, the software should not be considered distinct within the context of the contract.
- Highly interdependent or interrelated. When goods or services significantly affect each other such that the entity cannot transfer these goods or services independently, they are not distinct within the context of the contract. This indicator is closely related to the previous two indicators and is meant to capture situations where modification or integration may not be clear, but two or more goods and services promised in the contract clearly depend on each other (both directions) to provide the promised benefit to the customer.
The factors above are not exhaustive and should not be used as criteria. Determining whether a good or service is distinct requires judgment and an analysis of all relevant facts and circumstances. For example, one of the indicators states that if a good or service significantly modifies another good or service in the contract, it should not be considered distinct. However, simply modifying another good or service does not automatically make that good or service indistinct. An entity must determine whether the modification is significant. Similarly, a good or service may be distinct in the contract while still being interrelated with another good or service in a contract, provided it is not highly interrelated.
Below, we have compiled several case studies and SEC comment letters that analyze whether goods or services are distinct. This topic is one of the most frequently examined by the SEC in relation to ASC 606. To see other frequently examined topics, read SEC Comment Letters on ASC 606.
Plug Power Inc. (SEC Correspondence January 2022): Distinct Goods and Services
Plug Power Inc. is an American company engaged in the development of hydrogen fuel cell systems that replace conventional batteries in equipment and vehicles powered by electricity.
Plug Power’s customers qualified for the ITC (investment tax credit) by investing in its hydrogen fuel cell systems. The ITC allowed Plug Power’s customers to receive an immediate 30% tax credit on their purchases from Plug Power. In correspondence with the SEC dated January 19, 2022, the SEC sent Plug Power the following request:
“Please provide us with a specific and comprehensive analysis of your determination of whether the ITC is a separate performance obligation and how amounts have been allocated to revenue related to the ITC.”
In its response to the SEC, Plug Power references ASC 606-10-25-19 to determine whether the ITC is a separate performance obligation. This paragraph references two indicators for determining whether performance obligations are distinct:
1. Capable of being distinct
Plug Power does not sell the ITC separately from the equipment. However, Plug Power acknowledged that this fact is not determinative as to whether the ITC is capable of being distinct, so further analysis is required. Although the bank cannot benefit from the ITC without owning the equipment, Plug Power evaluated whether the equipment is considered a “readily available resource.” A readily available resource is a good or service that is sold separately or a resource that the customer has already obtained. It is not possible for the customer to acquire the equipment (from the Company or another entity) and separately acquire the ITC. As such, we do not believe the ITC is capable of being distinct.
2. Separately identifiable
To assess the second criteria, Plug Power references ASC 606-10-25-25 which states that:
“In assessing whether an entity’s promises to transfer goods or services to the customer are separately identifiable, …the objective is to determine whether the nature of the promise, within the context of the contract, is to transfer each of those goods or services individually or, instead, to transfer a combined item or items to which the promised goods or services are inputs.”
Plug Power notes that the ITC and the equipment are highly interrelated because the purchase of qualifying energy equipment gives rise to the customer’s ability to claim an ITC on its tax return. In other words, if the ITC was a promise in the contract, Plug Power could not fulfill its individual promises independently of each other. The ITC cannot legally be transferred separately from the equipment. As such, the ITC is not separately identifiable from other promises.
Because Plug Power determined that the ITC was not a separate performance obligation, no revenue was allocated to the ITC (January 2022 correspondence with the SEC).
Pulse Biosciences, Inc. (SEC Correspondence June 2022): Distinct Goods and Services
Pulse Biosciences, Inc. (Pulse) is a medicine company that sells a CellFX System, which typically includes a CellFX console, embedded software, handpieces, disposable tips, and CUs (Cycle Units). CUs authorize the customer to perform a procedure. Each procedure requires a specific number of CUs.
The SEC requested the following from Pulse:
“Tell us, and clarify in future filings, if the CUs are bundled together into a single performance obligation when you record the initial sale of the CellFX System pursuant to ASC 606-10-25-22.”
Pulse’s approach to determining if each part of the CellFX System, including the CUs, is a separate performance obligation is as follows:
The Company sells CUs on a standalone basis, following the initial system sale. The Company also sells all other goods (handpieces, tips, and consoles) on a standalone basis . . . Customers bear all rights and risks associated with the console ownership and can also sell their consoles to third parties. Thus, CUs (as well as all other goods sold by the Company) are capable of being distinct as customers can benefit from them together with other readily available resources (i.e., either previously purchased or separately sold Console).
Pulse supplies these goods separately and provides no service to integrate them into a combined output. Also, none of these goods significantly modify or customize any of the other goods sold by Pulse. Finally, these goods are neither highly interdependent nor highly interrelated. If an entity cannot fulfill its promise to transfer each of the goods independently, this may indicate that the goods are highly interdependent or highly interrelated. However, as discussed above, Pulse sells each of its goods separately. Pulse’s ability to fulfill its promise and sell any of its goods (including CUs) does not depend on its ability (or inability) to sell or transfer any of the remaining goods.
Pulse concluded that because each good is sold on a standalone basis, customers bear the rights and risks of console ownership, goods are not integrated in the final output, and goods are not significantly modified by the other goods, each good qualifies as separate performance obligation and is recorded as such (June 2022 correspondence with the SEC).
Case 1: Home Security Equipment, Installation, and Monitoring
Background
LiveSafe Security (LSS) is a leader in the residential security industry. LSS offers a variety of tiered packages to residential homeowners. Tiered packages differ in the quality and amount of security equipment included. In addition to the packages, customers must select monitoring services for periods of 1, 3, or 5 years. Customers cannot purchase the security equipment from LSS without subscribing to LSS’s monitoring service. Without LSS’s security monitoring, the equipment remains partially functional; however, security compromises are not electronically reported to LSS. For example, door detectors will still beep and the internal alarm will still sound if doors are opened after the house is locked down, but LSS will not monitor such occurrences.
LSS can typically install a system and start monitoring services within one week of a sale. Third parties routinely perform similar installation services, but they typically take twice as long. At the conclusion of the contract term, LSS customers often continue business with LSS by purchasing additional years of monitoring sold on a standalone basis. However, other security companies can provide monitoring services using LSS equipment.
Recently, LSS sold its standard package to a homeowner. The contract includes the following promised goods and services:
- Home security equipment, including motion sensor lights, door and window detectors, and a touchscreen control panel
- Equipment installation
- Three years of 24/7 security monitoring
Accounting Analysis
Capable of Being Distinct – LSS begins its analysis by considering if the goods and services of the contract are capable of being distinct. The security equipment appears to be distinct because the customer can use the equipment by installing it themselves and hiring another monitoring service, even though all customers must initially subscribe to LSS’s monitoring services. Further, the security equipment, without monitoring, maintains basic functionalities that provide benefits to the customer.
Both equipment installation and security monitoring are sold separately through third parties or on a renewal basis, also indicating that these services are distinct. Further, the customer can derive a benefit from the monitoring service because it can be used with the delivered equipment, which is a readily available resource. Given this analysis, each feature in the contract above is capable of being distinct.
Distinct within the Context of the Contract – Next, LSS must analyze if the promised goods or services are distinct within the context of the contract using the three indicators in ASC 606-10-25-21. These indicators are not exhaustive, and the presence of a single indicator is not determinative; thus, all the facts and circumstances should be considered.
- Significant integration service. LSS is not providing an integration service. For example, the control of the security equipment, equipment installation, and security monitoring are transferred to the customer in a sequence (e.g., the equipment gives the customer substantial features before the start of the monitoring term). Further, while the installation is, by nature, an integrative service, it does not alter the equipment or monitoring in a way that indicates LSS is providing a single deliverable. Thus, the promised goods and services do not appear to be separate inputs to a combined output in this arrangement.
- Significant modification or customization. The above goods or services do not significantly modify or customize one another. For example, the installation does not alter the equipment.
- Highly interdependent or interrelated. In this case, the customer can benefit from the security monitoring only after obtaining the security equipment, and installation is required for the equipment to provide its intended functionality. However, this does not necessarily mean the equipment and monitoring are highly interdependent or interrelated according to this factor. LSS must consider whether it could fulfill its promises to provide security equipment, installation, and monitoring separately. Although this customer is unable to purchase security equipment without also purchasing some period of security monitoring per company policy, LSS could fulfill its promise to provide these obligations separately. For example, LSS can deliver the equipment without monitoring and make monitoring available on a renewal basis after the contract. Further, the equipment maintains some significant functionality without monitoring. As such, the equipment and monitoring do not significantly affect one another. Similarly, the installation is not highly interdependent with the other contract features. LSS can deliver the other performance obligations even if the customer uses a third party for installation.
Summary
As described in the accounting analysis above, each promised good or service in the contract is capable of being distinct and is distinct within the context of the contract. As a result, LSS concludes that this contract contains the following distinct performance obligations:
- Home security equipment
- Equipment installation
- Three years of 24/7 security monitoring
Protalix BioTherapeutics, Inc. (SEC Correspondence Mar. 2019): Analysis of Distinct Goods or Services
In 2017 and 2018, Protalix entered into agreements with Chiesi Farmaceutici S.p.A. (“Chiesi”) to provide the license, clinical development, and manufacturing for a drug called pegunigalsidase alfa. Chiesi plans to promote and sell the drug. Originally, Protalix considered these three goods or services as one performance obligation because they were not capable of being distinct.
In a comment letter to Protalix in February 2019, the SEC asked, “why the license and research and development services, either alone or combined, are not separately identifiable from the supply obligation and thus do not meet the criteria in ASC 606-10-25-19(b).” In response, Protalix revised its position, concluding that the manufacturing service is not a performance obligation at all.
The Company’s obligation to manufacture the product upon approval essentially represents an optional future purchase by Chiesi at a standalone selling price. Accordingly, in effect, the contract contains one performance obligation for the license and R&D services and an option for Chiesi to purchase the manufactured product that does not represent a material right.
The license and R&D remain a single performance obligation because they are not distinct within the context of the contract. “Chiesi cannot benefit from the license without the R&D services. The R&D services are highly specialized and depend completely on the supply of the drug that can only be produced by the Company.”
Protalix restated its 2018 quarterly financial statements due to this error (March 2019 correspondence with the SEC).
Case 2: Landscaping Services
Background
Commercial Green Landscaping (CG) is a landscaping company operating in 32 national markets that specializes in landscape installations for SMB (small- and medium-sized business) commercial properties. Typical landscape installations begin with customers selecting landscapes from pre-designed blueprints provided by CG. Once a customer has selected a blueprint, CG may make some minor changes to accommodate the customer’s unique commercial property layout.
Recently, CG contracted with a small business to install a landscape based on a pre-designed blueprint. The contract contains the following items:
- Land gradation
- Irrigation system installation
- Sod installation
- Plants and shrubbery, including 12 trees and 36 bushes
- Cement curbing and landscaping rocks
The project is estimated to be completed in three months. The contract items above are occasionally provided by CG separately. Third parties routinely provide these same services on a standalone basis.
Accounting Analysis
Capable of Being Distinct – CG begins its analysis by considering if the promised goods and services are capable of being distinct. Generally, the fact that a good or service is sold on a standalone basis, either by the entity or third parties, is evidence that customers can benefit from the good or service separately. In this case, the customer owns the property to be landscaped and could purchase the contract services separately from CG or other vendors. Therefore, the promised goods and services are capable of being distinct.
Distinct within the Context of the Contract – Next, CG must analyze if the promised goods and services are distinct within the context of the contract using the three indicators in ASC 606-10-25-21. These indicators are not exhaustive, and the presence of a single indicator is not determinative; thus, all the facts and circumstances should be considered.
- Significant integration service. At contract inception, CG agreed to install a landscape that met the specifications of the chosen blueprint. The individual services included in the contract essentially become required inputs to achieve the specified design. In this way, CG provides a significant integration service of combining the land gradation, irrigation system, etc. into the output of a landscaped property that meets the customer’s desired output as specified in the original contract and blueprint.
- Significant modification or customization. The contract services do not significantly modify or customize one another. For example, the irrigation system installation does not customize or modify the land gradation or other landscaping items.
- Highly interdependent or interrelated. The different landscaping elements are often interrelated in the fact that these elements work together to accomplish a practical outcome. For example, land gradation and irrigation systems support sod installation, maintenance, and use. However, these items are not highly interdependent or interrelated for the purposes of being distinct within the context of the contract. This is because CG could transfer each contract service independently without significantly affecting the other, despite the sequential nature of landscaping services (i.e., an irrigation system is typically installed before the sod). Further, CG provides these services separately.
Summary
As described in the accounting analysis above, each promised good or service in the contract is capable of being distinct. However, due to the significant service of integration, the contract items are not distinct within the context of the contract. As such, CG concludes that the contract contains a single performance obligation.
Parsons Corporation (SEC Correspondence April 2019): Analysis of Distinct Services
Parsons Corporation is an engineering firm based in Centreville, Virginia. Parsons offers engineering, construction supervision, and construction services.
Parsons offers two combinations of services: engineering and construction supervision services, or engineering and construction services. The table below contains a description of each service.
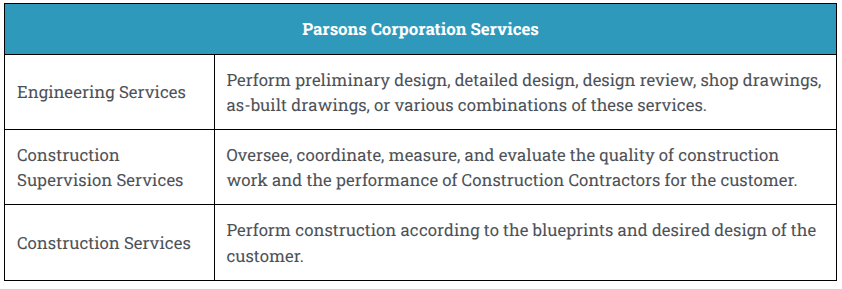 In April 2019, the SEC requested that Parsons clarify the differences between their two contract types and why some services were considered distinct:
Please further discuss the nature of the services provided in your engineering and construction supervision contracts and how you have concluded that these contracts contain two performance obligations. As part of your response, please explain to us how these arrangements differ from the engineering and construction contracts.
In response, Parsons explained that the engineering and construction supervision services are distinct within the context of the contract when combined in one contract:
The engineering drawings are used by the construction contractor to construct the asset and the company’s role in providing supervision services is to oversee the construction contractor’s performance in constructing the asset … The Company can fulfill engineering services without providing construction supervision services and can fulfill construction supervision services without providing engineering services.
In contrast, when Parsons provides engineering services and construction services in the same contract, these services are not distinct within the context of the contract. In this case, Parsons is “responsible for delivering to the customer a completed asset.” Parsons provides a significant integration service when it enters engineering and construction contracts, unlike the contract type above, in which Parsons only provides inputs. The construction is highly dependent on the engineering work and vice versa. Based on these factors, Parsons argued that the services are not distinct within the context of the contract, and Parsons accounts for this type of contract as one performance obligation (April 2019 letter to the SEC).
Case 3: Software License and Installation
Background
Track-to-Perform, Inc. (TPI) is a software company that specializes in financial planning and analysis tools for small businesses. The company offers a standard software program for various license durations. The standard program allows businesses to set departmental budgets and prepare financial reports and visualizations. TPI also offers software integration services, which require integrating TPI’s software with the customers’ financial databases and other company systems. These additional installation services are performed by a professional services team within TPI because the integration alters the software to create custom functionalities. TPI routinely sells software licenses separately, and third parties can perform the integration services.
Recently, TPI entered a contract with a professional services firm to provide the following:
- Two-year software license
- Professional installation services
The contracted installation services are scheduled to take a month to complete. The services include a full integration with the customer’s other systems, such as HR and sales (“integration installation”). TPI’s installation team has determined that the software itself will require significant modification to accommodate the integration. During the installation period, the customer does not have access to the software program.
Accounting Analysis
Capable of Being Distinct – TPI begins its analysis by considering whether the promised goods and services are capable of being distinct. TPI routinely sells the software license on a standalone basis, and third-party vendors often perform the software integration service contracted by the customer. Further, the customer can benefit from the installation services with the software license, which is a readily available resource once delivered. Given this analysis, each of the promised goods or services is capable of being distinct.
Distinct within the Context of the Contract – Next, TPI must analyze if the promised goods and services are distinct within the context of the contract using the three indicators in ASC 606-10-25-21. These indicators are not exhaustive, and the presence of a single indicator is not determinative; thus, all the facts and circumstances should be considered.
- Significant integration service. TPI’s professional installation services, specifically the software integration, create certain functionality essential to the customer’s intended use of the software. Therefore, without integration, the software would not meet the customer’s needs. Further, the customer does not have access to the software during the installation period. As such, the software license and the installation are inputs to create the combined output of an integrated software system. In this case, TPI is performing a significant integration service.
- Significant modification or customization. The modifications made to the software as part of the integration service are significant. TPI’s professional services team must modify the software code to create custom functionalities that connect with other systems. Therefore, the integration services significantly modify the software.
- Highly interdependent or interrelated. In this case, the customer can purchase the software without the professional installation services. This is because the integration service is available through a third party. As such, the software and the integration service are not highly interdependent.
Summary
As described in the accounting analysis above, each promised good or service in the contract is capable of being distinct. However, due to the significant integration service, the software license and integration service are not distinct within the context of the contract. Thus, one performance obligation exists in this contract.
Adobe Inc. (SEC Correspondence May 2019): Integrated and Interrelated Services
Adobe’s Creative Cloud provides on-premise software together with cloud-based features. In April 2019, the SEC sent a comment letter to Adobe requesting the following information:
Please provide us with a comprehensive analysis of how you determined that the Creative Cloud… on-premise software and the related cloud functionality are highly integrated and interrelated and are therefore accounted for as a single performance obligation. Refer to 606-10-25-21.
In response, Adobe argued that its software and cloud-based services are not distinct within the context of the contract. Adobe explained that customers require the combined functionality of both the licenses and the cloud-based features to complete their tasks. Adobe also provides a “significant service of integrating goods or services with other goods or services promised.” The services Adobe offers are actually inputs for one output because “[its] solution cannot provide its intended benefit to the customer without the customer having access to the cloud-based features and services, as each on-premise and on-device tool is integrated with the cloud-based features and services.”
Adobe’s analysis shows that the components of its Creative Cloud represent one performance obligation because they are not distinct within the context of the contract. For more examples with cloud applications, please see Adobe’s analysis of its Document Cloud service and Autodesk, Inc.’s discussion of its desktop and cloud services (May 2019 letter to the SEC).
Conclusion
The process of determining whether promised goods or services are distinct performance obligations is complex. To be considered distinct, a good or service must be both capable of being distinct and distinct within the context of the contract. As illustrated in this article, determining whether a promised good or service is distinct requires significant judgment, and entities should carefully consider all the facts and circumstances of the contract.
Editor’s Note:
This article reflects guidance under ASC 606, Revenue from Contracts with Customers, as currently codified, including subsequent amendments. While originally published in August 2020, the concepts discussed remain relevant, as ASC 606 has not undergone substantive changes affecting the topics involved in this article.
Resources Consulted


