


Published:
Mar 10, 2016
Updated:
Oct 10, 2026

Analysis of the scope considerations of ASC 606 and how ASC 606 interacts with other guidance, including an example of a transaction with mixed guidance.

Accounting Standards Codification (ASC) 606 provides standards that an entity must consider when recognizing revenue. Additionally, transactions partially within the revenue guidance and partially within the scope of other guidance must be divided into their respective portions, which are then accounted for separately. To divide these transactions, separation and measurement guidance from ASC 606 is only followed if the other guidance does not provide specific direction.
ASC 606 applies to transactions with customers, defined as “a party that has contracted with an entity to obtain goods or services that are an output of the entity’s ordinary activities in exchange for consideration.” Consequently, one scope consideration is whether the counterparty to a transaction is a customer (for additional guidance, see Definition of a Customer).
Additionally, ASC 606-10-15-2 provides the following explicit list of transactions with customers that are NOT in scope:
Contracts can be partially within the scope of ASC 606 and partially within the scope of another standard. In these cases, if the other topic provides direction for separation and measurement, that guidance should be followed first, with the remaining portion of the transaction being accounted for under ASC 606. Alternatively, if the other topic does not provide direction, then the guidance from ASC 606 on allocating transaction prices should be followed. The following flowchart summarizes the process for separating a transaction.

Non-warranty guarantees are outside the scope of ASC 606. In transactions that contain both guarantee and revenue elements, the guarantee must be recorded following the guidance in ASC 460, with the remaining portion of the transaction price allocated according to the revenue standard. Guarantees should be recognized as a liability at an amount equal to the estimated fair value (ASC 460-10-30-2). Because guarantees also meet the definition of a contingency, in some instances, the probable contingency could be larger than the estimated fair value. Although this is generally not the case, this exception may occur when a guarantee has a high probability of having a large impact. As a result, the contingency amount would be greater than the fair value of the guarantee, and the larger of the two must be recognized.
Similarly, derivatives must be measured at fair value (ASC 815-10-30-1), with the excess allocated according to the revenue standard. After the initial allocation, any subsequent change in fair value is accounted for according to relevant Generally Accepted Accounting Principles (GAAP). These adjustments will have no impact on the other performance obligations or on the way revenue is recognized.
Blendit Company (a manufacturer of high-end blenders) is interested in opening a smoothie shop in a new location near its remote corporate headquarters, so it can provide employees with complementary smoothies. Additionally, Blendit sees this as a means of developing a relationship with a new sales channel to sell its Pro3 blenders.
Sumptuous Smoothies is willing to open a new location and purchase 200 Pro3 blenders for its various locations if it can also negotiate a minimum revenue guarantee from Blendit to guarantee the revenue of the new location for 2 years. The total transaction price is $150,000, with the standalone selling price of the blenders and the fair value of the guarantee being $80,000 and $100,000, respectively. When the guarantee is considered a contingency, the amount that provides the best estimate within the range of possible losses is $60,000.
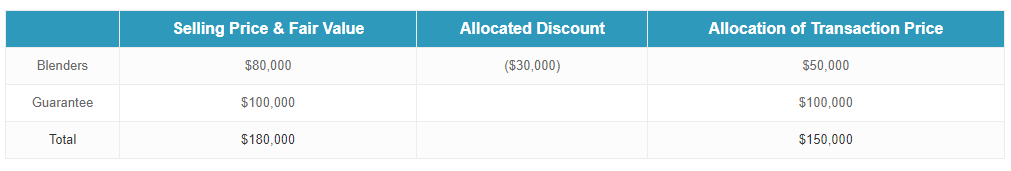
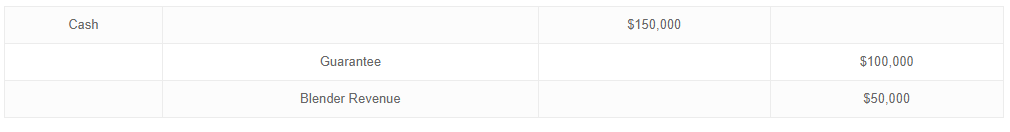
Because ASC 460 provides direction for measuring the guarantee at the greater of fair value or the contingency amount, the greater of these amounts ($100,000) is allocated to the guarantee and recorded as a liability, with the remainder ($50,000) allocated to the sale of the blenders. See the journal entry below:
ASC 842 specifically refers to ASC 606 for direction on allocating the transaction price for lessors. Consequently, contracts that contain both lease and revenue elements should be allocated based on relative selling price. Once consideration in an agreement has been separated into its lease and non-lease components based on relative selling price, consideration allocated to non-lease elements should be accounted for using guidance in ASC 606, while lease elements should be accounted for using guidance in ASC 842. It is also worth noting that lessors may elect to exclude certain taxes from contract consideration and must follow specific guidance for lessor costs paid directly by lessees to third parties. For additional guidance, see Standalone Selling Prices and ASC 606 and ASC 842 (Leases).
There are two primary considerations for whether a contract is subject to ASC 606. These include (1) whether the counterparty to the transaction is a customer and (2) whether the contract is within the scope (entirely or partially) of one of the exceptions listed. For transactions partially within the scope of ASC 606, other guidance should be used to the extent it provides specific measurement or separation guidance. This will result in any discount being allocated to the revenue portion of the transaction. However, when other relevant guidance provides no direction, then ASC 606 should be used to allocate the transaction price.
Editor’s Note:
This article was originally published on March 10, 2016, during the early implementation of ASC 606. It has since been reviewed and updated to align with current accounting standards, firm guidance, and prevailing interpretations.
FASB, ASU 2016-13: Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses on Financial Instruments. Pages 168–172.