


Published:
Jan 6, 2021
Updated:
Oct 10, 2026

Determine the transaction price of a contract with noncash consideration under ASC 606, including when and how to measure the variable consideration caused by fluctuating fair value.

In most business transactions, an entity receives cash in exchange for providing goods or services. However, many entities trade their goods or services for noncash consideration. Noncash consideration can take a variety of forms, including land, promised services, inventory, PP&E, and intangible assets. Equity instruments, such as stock, are the most common type of noncash consideration.
The purpose of this article is to analyze key accounting issues that arise under Accounting Standards Codification (ASC) 606 when recognizing revenue from transactions involving noncash consideration. These transactions mainly affect the third step of ASC 606, which is to determine the transaction price.
An entity that accepts noncash consideration in a revenue transaction follows the first two steps of the five-step method in the same manner as it would with cash consideration; the entity identifies the contract with the customer and then identifies the performance obligations. The third step—determining the transaction price—is where the nature of consideration has more of an impact on the entity’s approach to revenue recognition. For information about the other steps of the revenue recognition model, read The Five-Step Method.
The transaction price is the amount of consideration an entity expects to receive in exchange for transferring goods or services. Noncash consideration is measured at fair value at contract inception. Determining that fair value may require the use of valuation techniques when the amount is not readily observable. In some cases, more judgment will be needed to determine the fair value of the noncash consideration promised by the customer than the standalone selling price of the goods or services offered. To illustrate, publicly traded stock promised in exchange for equipment is likely easier to measure at fair value than the equipment itself would be. In contrast, a customer’s promise to transfer a piece of art as payment for a good or service may be more difficult to measure than the standalone selling price of the good or service. If an entity cannot reasonably determine the fair value of the promised noncash consideration, the standalone selling price of the goods or services promised to the customer is considered to be the transaction price (ASC 606-10-32-21 through 32-22).
The measurement date for determining the fair value of noncash consideration to be received from a customer is the date of contract inception, rather than the date when the noncash consideration is received or earned. The date of contract inception is the day that the criteria in ASC 606-10-25-1 are met (ASC 606-10-32-21). Read more about these criteria in Identify the Contract.
Noncash consideration with a variable fair value may be considered variable consideration. If so, the entity would be required to follow the guidance of ASC 606-10-32-5 through 32-14 to estimate the amount of consideration it will receive.
If the noncash consideration is variable only because of changes in its fair value due to its form (for example, a fixed number of shares or stock options whose market price fluctuates), it is not considered variable consideration. In that case, the transaction price is measured at the fair value of the noncash consideration at contract inception, and subsequent changes in market price are ignored for revenue recognition purposes.
In contrast, noncash consideration qualifies as variable consideration if the variability arises from factors other than its form. For example, if the number of shares or options to be received varies based on a performance target or other specified condition, that variability is treated as variable consideration under ASC 606-10-32-23.
Here is a table that helps differentiate between a variable consideration and one that is not.
Scenario | Variable Consideration | Guidance |
Payment is a fixed number of shares/options; only the market price fluctuates | NO | Measure at fair value at contract inception; ignore price changes |
The number of shares/options varies based on performance or another condition | YES | Apply variable consideration/constraint guidance under ASC 606-10-32-23 |
If noncash consideration includes variability for multiple reasons, the variable consideration guidance applies only to the portion of variability that arises from factors other than the form of the consideration. To learn more, read Variable Consideration and the Constraint.
Consider a case where Entity A enters a contract with Entity B to perform consulting services that would normally be valued at $51,000. Entity A determines that the service is a single performance obligation. Instead of receiving cash from Entity B, Entity A agrees to be paid in 1,000 shares of common stock of Entity B. During the year, the following events occurred:
Issue: On what day is the noncash consideration measured? Is the noncash consideration remeasured on any later dates?
Analysis: Entity A measures the noncash consideration (shares of Entity B) at its fair value on the contract inception date of Jan. 1, 2027. The fair value of the 1,000 shares on this date is $50,000. Entity A recognizes $50,000 of revenue when (or as) it satisfies the performance obligation.
The fair value of the common stock varies only due to its form and not due to Entity A’s performance; therefore, the consideration does not qualify as variable consideration. Accordingly, changes in the stock’s fair value are not included in the transaction price. The noncash consideration is measured at fair value on the contract inception date for purposes of determining the transaction price and is not subsequently remeasured for revenue recognition under ASC 606. Once the entity’s right to the shares or stock options becomes unconditional, the related asset (typically a receivable) is accounted for under other applicable GAAP, such as ASC 321.
Consider a case where Entity A enters a contract with Entity B to perform consulting services that would normally be valued at $51,000. Entity A determines that the service is a single performance obligation. Instead of receiving cash from Entity B, Entity A agrees to be paid in stock options of Entity B.
During the year, the following events occurred:
Issue: On what day is the noncash consideration measured? Is the noncash consideration remeasured on any later dates?
Analysis: In this example, the fair value of the noncash consideration could change as a result of 1) the form of the stock options and 2) reasons other than its form. Stock options naturally fluctuate in value due to their form, and the fair value of the consideration also varies based on the day Entity A completes its work. The guidance on variable consideration (ASC 606-10-32-5 through 32-14) should only be applied to the variability resulting from reasons other than the form of the consideration (ASC 606-10-32-23). Thus, any changes in the fair value of individual stock options should not affect the transaction price. Only the variability based on the day Entity A completes its work will affect the transaction price. While price fluctuations are ignored for revenue recognition, the entity should evaluate the related contract asset for impairment in accordance with ASC 326 on credit losses (see ASC 606-10-45-3).
The results are as follows:
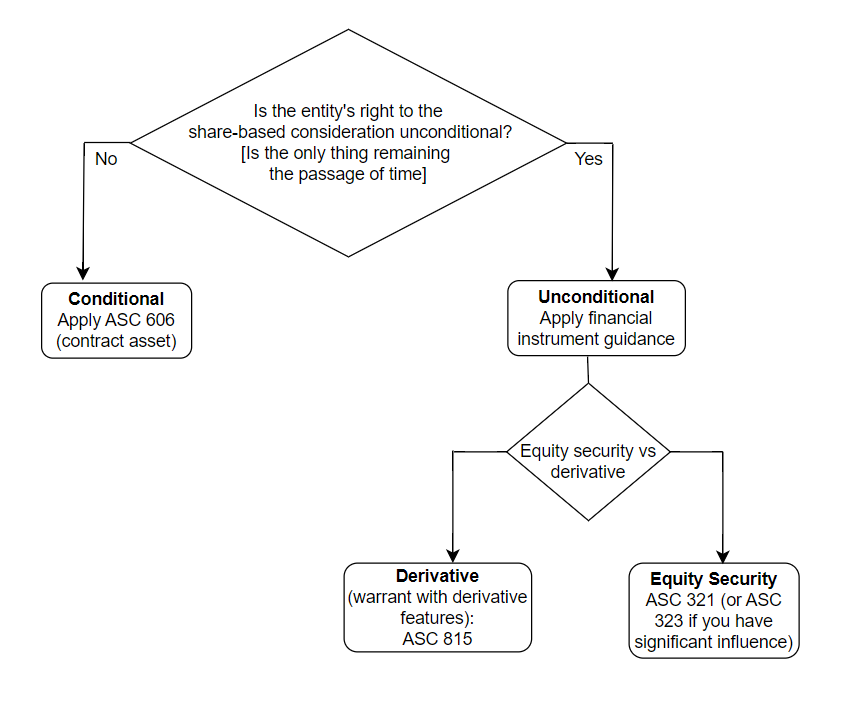
Accounting Standards Update 2025-07 added paragraph 606-10-15-3A to clarify the scope of ASC 606 for share-based noncash consideration received from a customer. Under this amendment, an entity applies ASC 606—including the guidance in paragraphs 606-10-32-21 through 32-24—to contracts in which a customer transfers shares, share options, warrants, or other equity instruments in exchange for goods or services.
The amendment clarifies that other GAAP, including ASC 815 and ASC 321, do not apply to share-based noncash consideration unless and until the entity’s right to receive or retain that consideration becomes unconditional. A right is considered unconditional when only the passage of time is required before payment is due, consistent with ASC 606-10-45-4.
If an entity has transferred some distinct goods or services in the contract but must still satisfy other performance obligations to be unconditionally entitled to share-based consideration, the arrangement remains within the scope of ASC 606, and a contract asset is recognized as a contract asset. Once the right becomes unconditional, the contract asset is derecognized, and a receivable is recognized for the equity instruments. The measurement of this receivable, indexed to financial instruments, is guided by ASC 321 or ASC 815, as applicable.
Accordingly, share-based noncash consideration remains within the scope of ASC 606 while the entity is still performing under the contract or meeting performance-based conditions. During this period, changes in the fair value of the shares, warrants, or options do not affect the transaction price, which is measured at contract inception in accordance with ASC 606-10-32-21 through 32-24. Similarly, the measurement of any contract assets based on the original transaction price measure is within the scope of ASC 606, but subject to credit loss assessments according to subtopic 326-20.
The following diagram summarizes when share-based noncash consideration transitions from ASC 606 to other applicable GAAP.
On January 1, 20X7, an entity enters into a contract to sell 5,000 units of Product A at $100 per unit. If the entity delivers all 5,000 units within two years, the customer will also grant 100 stock warrants. The estimated fair value of the warrants at contract inception is $100,000.
Each unit represents a separate performance obligation satisfied at a point in time. Based on experience, the entity expects it will deliver all 5,000 units within the required time period and concludes the bonus is not constrained.
Step 1: Determine the Transaction Price
Cash consideration: 5,000 units × $100 = $500,000
Estimated fair value of warrants (at contract inception): $100,000
Total transaction price: $500,000 + $100,000 = $600,000
Transaction price per unit: $600,000 / 5,000 = $120 per unit
Even though the warrants may fluctuate in market value, their fair value is measured at contract inception for purposes of determining the transaction price under ASC 606.
Year 1 (20X7) | Year 2 (20X8) |
The entity delivers 3,000 units. | The entity delivers the remaining 2,000 units. |
Revenue recognized: 3,000 × $120 = $360,000 | Revenue recognized: 2,000 × $120 = $240,000 |
Cash received: 3,000 × $100 = $300,000 | Cash received: 2,000 × $100 = $200,000 |
Contract asset recorded: $60,000 (portion of warrant value earned) | Additional contract asset recorded: $40,000 (bringing the total contract asset to $100,000) |
The entity does not adjust revenue for changes in the fair value of the warrants. However, the entity evaluates the contract asset for expected credit losses in accordance with ASC 326 (see ASC 606-10-45-3). | After all 5,000 units are delivered, the entity’s right to the 100 warrants becomes unconditional (only the passage of time remains before issuance). At that point: The contract asset is derecognized. The warrants are accounted for under other applicable GAAP, such as ASC 321 or ASC 815. |
Key Takeaways
Oftentimes, a customer contributes goods or services to help complete a contract. In such cases, the entity determines whether it retains control of those goods or services after the contract is completed. If the entity retains control, those goods or services are accounted for as noncash consideration. For example, assume that a customer contributes specific supplies to a manufacturer to complete a contract. If the manufacturer uses the supplies to complete the customer’s order and receives no additional benefit, those supplies are not considered noncash consideration. However, if the manufacturer retains excess supplies after satisfying its contractual obligations and subsequently uses those supplies to fulfill other contracts, the remaining supplies would be treated as noncash consideration (ASC 606-10-32-24).
Under the five-step revenue recognition model in ASC 606, entities should exercise judgment when determining the transaction price for contracts involving noncash consideration. Noncash consideration is measured on the date of contract inception at its fair value. If fair value is not determinable, the standalone selling price of the goods or services should be used. Entities should follow the guidance for variable consideration if the amount of noncash consideration will vary due to reasons other than its form. Customer contributions towards the completion of the contract may also represent noncash consideration under certain circumstances. Importantly, changes in fair value resulting solely from the form of noncash consideration do not affect revenue under ASC 606.
Effective for annual reporting periods beginning after December 15, 2026, ASU 2025-07 clarifies that share-based noncash consideration from a customer remains within the scope of ASC 606 until the entity’s right to receive or retain that consideration becomes unconditional. This amendment clarifies the interaction between ASC 606 and other Topics, such as ASC 815 and ASC 321, but does not change the fundamental measurement principles for determining the transaction price discussed above.